Deadlines & Filing
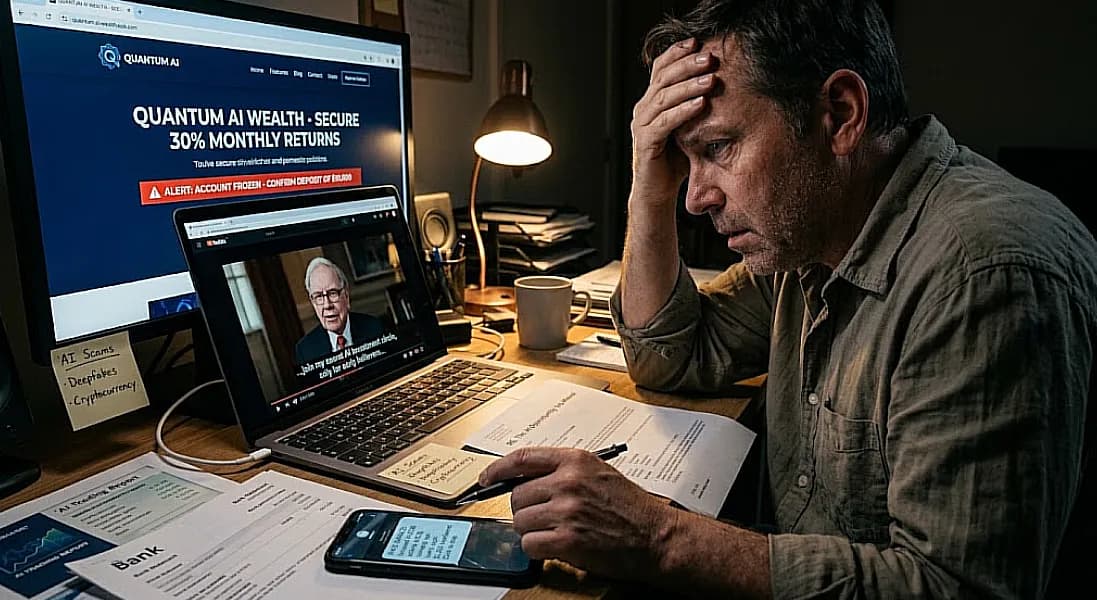
AI financial scams are becoming more convincing in 2026, using deepfake videos, cloned voices, and fake investment platforms to deceive consumers. Learn how to identify dangerous warning signs, verify investment opportunities, protect your financial accounts, and take action if you lose money to fraud.
Artificial intelligence is changing how people manage money, research investments, and make financial decisions. From automated trading tools to personalized budgeting apps, AI can offer genuine benefits. However, the same technology is also helping criminals create convincing financial scams that are increasingly difficult to recognize.
A fraudulent investment advertisement may feature a realistic video of a famous entrepreneur. A phone call may sound exactly like a family member asking for emergency money. A fake trading application may display a professional dashboard, rising account balances, and apparently successful investments. These details can make a dishonest operation look legitimate, even when the money deposited into it is being stolen.
In 2026, protecting your finances requires more than recognizing suspicious emails or avoiding unfamiliar websites. Consumers must understand how AI financial scams work, how criminals build trust, and how to verify financial opportunities before sending money.
The Federal Bureau of Investigation's 2025 Internet Crime Report, released in April 2026, recorded more than one million complaints about cyber-enabled crime and nearly $21 billion in reported losses. The report identified investment fraud as a major source of financial damage and highlighted the growing role of AI in sophisticated scams. These figures represent reported incidents, not every fraud experienced by American consumers. Nevertheless, they illustrate the scale of the problem.
The good news is that understanding the tactics behind these schemes can help you recognize danger earlier, protect your accounts, and respond more effectively if something goes wrong.
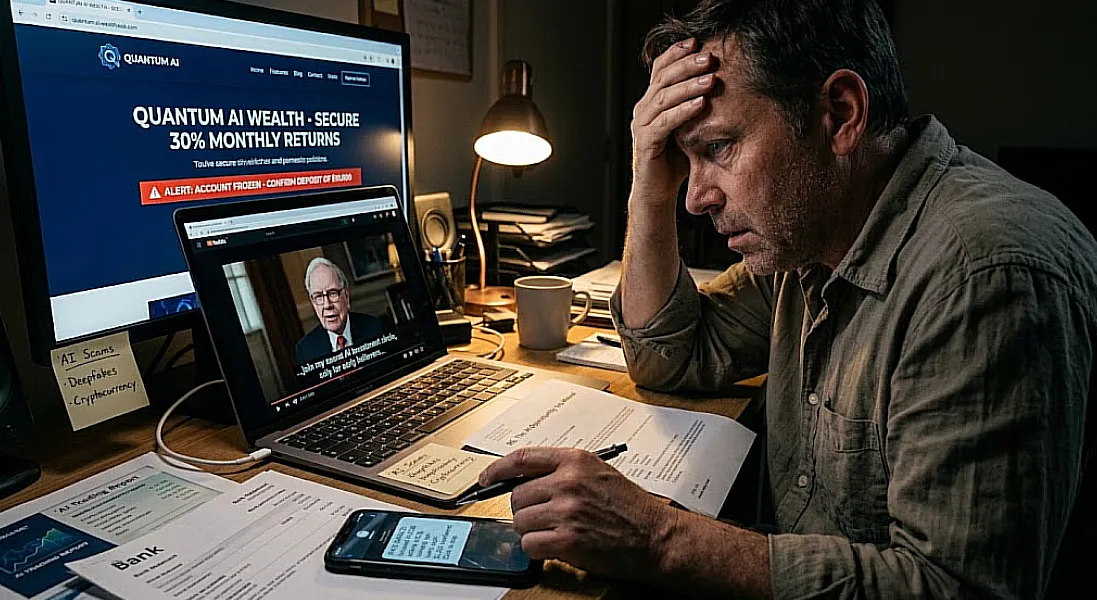
AI financial scams are fraudulent activities in which criminals use artificial intelligence to deceive people into revealing financial information, transferring money, purchasing fake investments, or granting access to their accounts.
Traditional scams often rely on fabricated stories, impersonation, fake documents, or promises of unrealistic profits. AI can make these tactics more convincing by helping criminals generate realistic voices, images, videos, written messages, and websites.
For example, a scammer might use AI to produce a video of a well-known investor supposedly recommending a new cryptocurrency. Another criminal might create a chatbot that answers questions about a fake investment platform, giving the impression that customers are interacting with a professional financial company.
AI can also help scammers personalize their approach. Instead of sending identical messages to thousands of people, criminals can generate tailored communications that reflect a person's interests, profession, financial concerns, or publicly available information.
The technology itself is not inherently fraudulent. Legitimate banks, investment firms, and financial technology companies also use AI. The danger arises when criminals exploit it to impersonate trusted people, manufacture evidence, or persuade consumers to make financial decisions under false pretenses.
For consumers, the essential distinction is between a legitimate financial service using technology and a fraudulent operation using technology to manufacture trust.
Financial scams have existed for centuries, but modern AI tools can make certain forms of deception faster, cheaper, and more convincing.
Criminals can use publicly available photographs, videos, and audio recordings to imitate real people. A convincing imitation of a business executive, financial adviser, celebrity, or family member can make a fraudulent request appear credible.
The FBI has warned that generative AI can produce persuasive text, images, audio, and other material that criminals use in financial fraud. These capabilities can reduce the obvious errors that previously helped people identify suspicious communications.
AI-generated messages may include accurate references to a person's workplace, hobbies, recent activities, or financial interests. This personalization can make a stranger appear more familiar and trustworthy.
A person who frequently watches investment videos, for example, might encounter a tailored advertisement promising access to an exclusive trading community. The message may look relevant to their interests, even though the people behind it are attempting to steal deposits.
A fraudulent investment website does not necessarily look suspicious. It may contain detailed explanations, customer support features, charts, testimonials, and a dashboard displaying account performance.
AI can help criminals produce this material efficiently. However, a professional appearance does not establish that a company is registered, that its investments exist, or that customers can withdraw their funds.
A scam may begin with a social media advertisement, continue through a private messaging group, and conclude with a request to deposit money through a website or cryptocurrency wallet.
Each interaction may reinforce the previous one. A fake adviser may introduce the opportunity, fabricated testimonials may provide social proof, and a simulated account balance may suggest that the investment is succeeding.
After someone loses money, criminals may approach them pretending to be investigators, lawyers, cryptocurrency specialists, or recovery companies. They may claim that a payment is required to unlock the original funds.
This creates a second opportunity for fraud. Anyone who has already suffered a financial loss should be especially cautious about unsolicited promises to recover it.
Understanding the main forms of AI-assisted financial fraud can help you recognize how criminals approach potential victims.
Deepfakes are manipulated or AI-generated videos, images, or audio recordings that imitate real people. In financial scams, criminals may use them to make it appear that a celebrity, business executive, financial expert, or public figure endorses an investment opportunity.
Imagine seeing a video in which a famous entrepreneur explains how an unfamiliar trading platform supposedly generates consistent daily profits. The person appears to speak naturally, the company logo looks authentic, and the advertisement directs viewers to register immediately.
The video might be entirely fabricated.
Criminals may also edit genuine interviews, combine authentic footage with synthetic audio, or place misleading captions over legitimate recordings. Consequently, a video does not have to be completely AI-generated to become part of a fraudulent campaign.
The U.S. Securities and Exchange Commission, alongside other investor protection organizations, has specifically warned about AI-enabled investment fraud involving deepfake audio and video, fabricated endorsements, and misleading claims about investment opportunities.
How to protect yourself: Never invest solely because a familiar face appears in an advertisement. Search for the endorsement on the person's verified channels, independently locate the company's official website, and investigate the investment itself. Even a genuine endorsement does not guarantee that an investment is suitable or safe.
Voice cloning allows software to imitate a person's voice using audio samples. Criminals may exploit this capability to impersonate relatives, friends, colleagues, or company executives.
A typical scam begins with an urgent phone call. The caller sounds like someone you know and claims to have been involved in an accident, lost access to an account, or encountered an emergency requiring immediate payment.
In a business setting, an employee might receive a call that appears to come from a senior manager requesting an urgent transfer to a new bank account.
The scammer's objective is to create emotional pressure or exploit workplace authority before the recipient has time to verify the request.
A familiar voice is not sufficient proof of identity. Audio can be copied, manipulated, or generated, and criminals may combine voice cloning with personal information collected from social media.
How to protect yourself: End the call and contact the person using a number already saved in your contacts or obtained from an independently verified source. For family emergencies, establish a private verification phrase that is not publicly shared. For workplace payments, require a separate approval process and confirm changes to payment instructions through an established channel.
Some fraudulent applications advertise AI-powered trading systems that supposedly analyze markets, predict price movements, or generate profits automatically.
Their marketing may include phrases such as algorithmic intelligence, institutional-grade trading, predictive analytics, or automated wealth generation. These descriptions can sound sophisticated without providing meaningful evidence of a legitimate investment service.
A fraudulent platform may display a balance that increases every day. Customers might initially be permitted to withdraw a small amount, encouraging them to invest more. Once larger sums are deposited, withdrawals may be blocked or additional payments demanded.
In such cases, the displayed profits may be entirely fictional. The application is designed to persuade users that their money is growing when the operator is actually controlling the funds.
Not every automated trading platform is fraudulent, and genuine financial companies use algorithms. The problem is the unsupported promise of reliable profits, combined with inadequate transparency or deceptive business practices.
How to protect yourself: Verify the legal identity of the company, the individuals operating it, and any required registrations. Review the investment strategy, risks, fees, and custody arrangements. Do not assume an application is legitimate because it appears in an app store, has attractive graphics, or provides a convincing demonstration.
Cryptocurrency scams often combine AI-generated promotional content with fake trading platforms, impersonation, and social engineering.
A criminal may contact someone through social media or a messaging application and gradually develop a relationship. After trust has been established, the person introduces a cryptocurrency investment opportunity that supposedly produces unusually high returns.
The victim may be directed to a website that displays impressive profits. Encouraged by these apparent results, the victim deposits more money. Eventually, the platform demands additional payments or stops responding altogether.
The FBI describes a form of cryptocurrency investment fraud commonly known as pig butchering. These schemes often involve prolonged relationship-building before the victim is persuaded to invest through a fraudulent platform. AI-generated communications and deepfakes can make these interactions more convincing.
A scammer may claim that an AI trading bot identifies profitable opportunities, that a private group has exclusive market information, or that a limited-time opportunity will disappear unless the victim acts immediately.
How to protect yourself: Do not transfer cryptocurrency to an investment platform solely because someone you met online recommends it. Verify the business independently, understand who controls the wallet or account, and be suspicious of guaranteed returns. Remember that cryptocurrency transfers can be difficult or impossible to reverse.
AI-assisted impersonation can make it easier for criminals to pose as financial advisers, portfolio managers, market analysts, or employees of legitimate investment companies.
A fraudulent adviser may have a convincing profile photograph, professional-looking credentials, a detailed biography, and a history of apparently insightful market commentary. Some may use deepfake videos during online meetings or send fabricated documents claiming to establish their qualifications.
They might recommend stocks, cryptocurrency, foreign exchange trading, or other investments while insisting that clients transfer money to an account they control.
Another variation involves impersonating a real financial professional. Criminals may copy the person's name and photograph, create a lookalike website, or contact potential victims using a similar email address.
How to protect yourself: Verify an adviser's identity and professional status independently. In the United States, use the SEC's Investment Adviser Public Disclosure resources and FINRA's BrokerCheck, as appropriate for the professional and service involved. Contact the firm through independently sourced contact details rather than those supplied by the person approaching you.
Investment groups on messaging applications and social media may contain numerous accounts that appear to be ordinary investors sharing profitable trades.
Some groups use fabricated testimonials, synthetic profile photographs, coordinated messages, and manipulated screenshots to create the impression that many people are earning money.
A supposed expert may share market predictions while group members post images of successful withdrawals. Participants who express doubts may be ignored, pressured, or told that they have missed an opportunity.
In reality, some of these accounts may be controlled by the same operators. The apparent community may exist primarily to persuade newcomers to deposit money.
AI can help generate different writing styles and personalized conversations, making coordinated deception harder to recognize.
How to protect yourself: Treat unsolicited investment groups with caution, particularly when members repeatedly promote one platform or discourage independent research. Do not rely on screenshots, anonymous testimonials, or the apparent popularity of a recommendation. Verify claims through independent financial sources and official company records.
No single warning sign proves that a financial opportunity is fraudulent. However, several warning signs appearing together should prompt you to stop and investigate.
Claims of guaranteed profits, unusually high returns, or consistent daily earnings with little risk are among the most important warning signs.
Legitimate investments involve uncertainty. Market conditions change, asset prices fluctuate, and even experienced professionals can lose money.
A platform claiming that its AI eliminates investment risk should be treated with skepticism. An algorithm may analyze information, but it cannot guarantee future market outcomes.
Scammers frequently create artificial deadlines. They may claim that an opportunity is available only to a few investors or that a special entry price will disappear within minutes.
The purpose is to prevent careful research. A legitimate investment should withstand reasonable questions and independent verification.
Never let urgency replace due diligence.
A request to transfer funds to an unfamiliar cryptocurrency wallet, personal account, or unrelated business should trigger additional scrutiny.
Cryptocurrency is not inherently fraudulent, but transfers may be difficult to reverse. Scammers may favor payment methods that reduce the likelihood of recovering stolen funds.
Be particularly cautious if an investment company changes its payment instructions unexpectedly or asks you to send money to a third party.
A platform may display profits but refuse to release the money. The operator might demand additional deposits for taxes, verification, account upgrades, liquidity, or withdrawal processing.
Do not assume these demands are legitimate simply because the website uses financial terminology.
Before sending any additional money, contact your financial institution and independently investigate the platform. A request to pay more money to access supposedly existing funds can be part of the fraud itself.
Financial services may be subject to federal or state registration requirements, depending on the activity, products, and parties involved. A company that refuses to identify its legal entity or provides unverifiable registration details deserves careful scrutiny.
Search official regulatory databases rather than trusting certificates, screenshots, or links supplied by the promoter.
Registration alone does not guarantee an investment's success or eliminate fraud risk. It is one part of a broader verification process.
Criminals may impersonate government officials, bank employees, regulators, or law enforcement officers to convince victims to transfer funds or disclose sensitive information.
Be especially wary of anyone claiming that you must move your savings to a supposedly safe account, pay a fee to prevent an investigation, or provide authentication codes over the phone.
Independently contact the relevant institution using a verified number. Never rely solely on the caller's display name, voice, identification image, or explanation.
A few deliberate checks can help you separate legitimate financial services from fraudulent operations.
Start by identifying the company that actually operates the service. Look for its legal name, physical business information, leadership, regulatory status where applicable, and written disclosures.
Search for the company name alongside terms such as fraud, complaint, withdrawal problems, and regulatory action. Read beyond testimonials on its own website.
Be aware that criminals may impersonate legitimate companies, so finding a real business with a similar name is not enough. Confirm that the website domain, contact details, and payment instructions genuinely belong to the business you intend to use.
The appropriate database depends on the investment and service being offered.
Some financial activities are regulated by different authorities, and not every legitimate financial service falls under the same registration framework. If you are unsure which rules apply, consult the relevant regulator or a qualified professional.
Do not accept a registration number simply because a promoter supplies one. Check it yourself and make sure the registered entity matches the company contacting you.
If an advertisement claims that a celebrity, executive, or financial expert recommends an investment, look for the original statement on a verified channel.
Search for the exact wording of the endorsement and investigate whether reputable news organizations or the company itself have confirmed it.
However, the absence of a public endorsement is not the only issue. Even an authentic endorsement does not prove that an investment is safe, profitable, or appropriate for your financial circumstances.
Before depositing money, determine what you are buying, how the investment supposedly generates returns, what fees apply, and how you can withdraw funds.
Look for clear information about the assets involved, investment risks, account custody, and the legal entity responsible for holding customer money.
If the explanation consists mainly of AI terminology and promises of exceptional performance, request more detailed documentation. If the operator cannot explain the product clearly, do not proceed.
A small initial deposit is not a reliable way to establish legitimacy. Some scams allow early withdrawals to build confidence before encouraging victims to transfer larger sums.
Instead of testing the platform with money, verify the company, its regulatory status, and its operations first. Do not risk funds you cannot afford to lose, and never borrow money simply to participate in an unfamiliar investment scheme.
Use strong, unique passwords and enable multifactor authentication wherever available. Consider using a password manager and account alerts for unusual transactions.
Never share one-time verification codes, recovery phrases, private cryptocurrency keys, or remote-access permissions with someone who contacts you unexpectedly.
For large transfers, establish a cooling-off period or require independent confirmation. These safeguards can make it harder for a convincing impersonation to trigger an immediate financial loss.
Discovering that an investment was fraudulent can be stressful, especially if the scam involved a trusted voice, a convincing video, or an account that appeared to show genuine profits.
Acting quickly may improve your chances of limiting further losses. Recovery is not guaranteed, but several practical steps can help.
Do not make additional deposits to unlock withdrawals, increase account limits, pay supposed taxes, or satisfy demands from the person operating the platform.
Scammers may claim that one final payment will release your balance. They may also threaten account closure or legal action to make you act quickly.
Save the messages and payment instructions, but do not continue negotiating or sending funds simply because the operator promises a solution.
If you paid through a bank transfer, debit card, credit card, payment application, or wire service, contact the provider immediately using an official phone number or application.
Explain that you suspect fraud and ask whether the transaction can be stopped, recalled, disputed, or reviewed. The options depend on the payment method, timing, applicable rules, and circumstances.
If your account credentials or card information may have been compromised, ask the institution about securing the account, replacing affected cards, changing access credentials, and monitoring for unauthorized activity.
Do not assume a payment can be reversed. Nevertheless, reporting it quickly is generally better than waiting.
Change passwords for affected accounts, beginning with your email and financial accounts. If you reused the same password elsewhere, change it on those services as well.
Enable multifactor authentication, review recent account activity, revoke suspicious sessions, and contact your bank if someone may have accessed your account.
If you installed software at a scammer's request or granted remote access to your computer or phone, disconnect the device from the network if necessary and seek trusted technical assistance. Do not use contact details provided by the suspected scammer.
If sensitive identity information was exposed, visit IdentityTheft.gov for guidance on the appropriate protective measures.
Keep copies of anything that may help a bank, payment provider, regulator, or investigator understand what happened.
Useful evidence includes:
Preserve original records where possible. Avoid editing screenshots in ways that remove useful details, and do not delete the conversations simply because they are upsetting.
In the United States, several reporting channels may be relevant:
Federal Trade Commission (FTC): Report suspected fraud through ReportFraud.ftc.gov. The FTC collects reports about scams and deceptive business practices.
FBI Internet Crime Complaint Center (IC3): Submit a report through IC3.gov for suspected online investment fraud, cryptocurrency scams, and other internet-enabled crimes. Include transaction details and information about how the scam began.
Securities and Exchange Commission (SEC): If the matter involves a suspected securities fraud or misleading investment promotion, consult the SEC's official website for investor assistance and reporting options.
State financial regulators: Depending on the circumstances, your state's securities regulator or other financial regulator may also be able to receive a complaint.
A report does not guarantee reimbursement or an investigation into every individual case. However, accurate reporting may help authorities identify patterns, connect related complaints, and pursue appropriate enforcement action.
After a victim reports fraud or discusses it online, another criminal may appear claiming to be able to recover the stolen money.
These individuals may impersonate investigators, lawyers, blockchain analysts, or specialist recovery firms. They may demand an advance fee, request cryptocurrency transfers, or ask for access to financial accounts.
Some legitimate professionals provide asset-recovery or legal services, but no one should be trusted solely because they claim to have special connections or guaranteed results.
Verify any service independently, understand its fees and terms, and be suspicious of anyone requesting additional money before providing credible evidence of what they can actually do.
The possibility of recovering money depends on how it was sent, how quickly the fraud was reported, whether the funds remain accessible, and the legal circumstances.
A bank or payment provider may be able to investigate certain transfers or transactions. Some card payments may qualify for dispute procedures. Cryptocurrency transactions, however, are often difficult to reverse once confirmed on a blockchain.
Recovery may sometimes involve financial institutions, law enforcement, regulators, legal proceedings, or cooperation with other jurisdictions. None of these routes guarantees that the money will be returned.
It is also important to distinguish between recovering money and recovering control of an account. If a criminal has compromised your bank account, securing it may prevent additional losses even if the original payment cannot be recovered.
Avoid anyone who claims that recovery is certain, demands secrecy, or insists that you pay an unexplained fee immediately. A second scam can deepen the financial damage caused by the first.
Although criminals can misuse AI, consumers can also use technology to support safer financial decisions. The key is to treat AI as an assistant rather than an authority.
AI tools can help summarize publicly available company information, explain unfamiliar investment terminology, compare fee structures, or generate questions to ask a financial adviser.
For example, you might ask an AI assistant to explain how an investment product works, identify risks mentioned in a prospectus, or create a checklist for researching a brokerage firm.
However, AI-generated answers can contain mistakes or rely on incomplete information. Verify important claims through original documents and official regulatory resources.
Many banks and financial services offer transaction notifications, suspicious-login alerts, spending controls, and other account-security features.
Enable appropriate alerts so that you can identify unexpected transactions quickly. Review account activity regularly, particularly after interacting with an unfamiliar service or receiving a suspicious message.
Where available, use transaction limits and additional approval requirements for larger transfers.
Agree on a simple process for handling urgent requests for money.
Family members can establish a private verification phrase or agree to call each other back using known contact information. Businesses can require two-person approval for significant payments and independent confirmation of changed bank details.
These procedures are useful even without AI. They become particularly important when an unfamiliar voice or convincing video can imitate someone you trust.
Do not move directly from a social media advertisement to depositing money.
Instead, independently research the opportunity, identify the company, verify relevant credentials, review the terms, and consider the risks. Use trusted financial institutions and official channels when opening accounts or transferring funds.
Taking time to investigate creates a barrier between persuasive marketing and an irreversible financial decision.
AI investment tools are not automatically illegal or fraudulent. Legitimate businesses use algorithms for research, portfolio analysis, customer support, risk assessment, and other financial activities.
However, the presence of AI does not establish that a company is trustworthy or that its product is effective. A genuine tool may still be unsuitable for a particular investor, while a fraudulent platform may use sophisticated technology to conceal its activities.
Legal obligations depend on the services offered, the assets involved, the business structure, and applicable federal and state laws. Some activities may require registration or other regulatory compliance, while others may be subject to different rules.
Consumers should distinguish between three separate questions:
An affirmative answer to one question does not automatically answer the others.
Be especially cautious when a promoter suggests that regulators have approved an investment's profitability or that AI technology eliminates ordinary investment risks. Regulatory registration is not a guarantee of performance, and no algorithm can promise that markets will always move in a favorable direction.
Avoiding AI financial scams is not simply about identifying suspicious videos or recognizing cloned voices. It requires consistent financial habits that reduce the chance of making decisions under pressure.
First, establish a personal rule against investing in opportunities you have not independently researched. A convincing advertisement, a recommendation from an online acquaintance, or a displayed profit is not sufficient evidence.
Second, maintain strong account security. Use unique passwords, multifactor authentication, transaction notifications, and secure recovery methods. Keep devices updated and be cautious about installing unfamiliar applications.
Third, create a verification process for unusual requests. When someone asks for an urgent payment, confirm their identity through a separate communication channel. When an investment platform changes its payment details, verify the change directly with the organization using trusted contact information.
Fourth, maintain realistic expectations about investing. Diversification, careful research, and an understanding of risk are more useful foundations than promises of quick wealth. If an opportunity depends on secrecy, urgency, or guaranteed profits, step away until the claims can be independently verified.
Finally, talk openly about financial scams with family members. People may hesitate to report fraud because they feel embarrassed or fear being judged. A supportive environment can make it easier to recognize warning signs and seek help before losses grow.
Financial security does not require you to distrust every new technology. It requires you to verify important claims, protect access to your money, and avoid allowing persuasive technology to replace sound judgment.
AI financial scams are making financial fraud more convincing by helping criminals imitate trusted people, manufacture investment endorsements, personalize messages, and create realistic-looking trading platforms. Deepfake videos, voice cloning, fraudulent investment applications, and fake cryptocurrency opportunities can all be used to persuade consumers to transfer money under false pretenses.
The most effective defense is a combination of independent verification, secure financial accounts, realistic investment expectations, and a willingness to pause when something feels urgent or unusually profitable.
Before investing, research the company, check relevant regulatory records, understand the risks, and verify endorsements through reliable sources. Never assume that a professional website, familiar voice, convincing video, or apparently successful trading dashboard proves that an opportunity is legitimate.
If you suspect that you have been scammed, stop sending money, contact your bank or payment provider, secure compromised accounts, preserve evidence, and report the incident through the appropriate U.S. authorities. Be equally cautious of anyone who promises to recover your money for an upfront fee.
AI will continue to influence the financial world, creating both useful tools and new opportunities for abuse. Consumers who combine technological awareness with careful financial habits will be better positioned to recognize deception, protect their savings, and make informed decisions in 2026 and beyond.

Written by
BeastBeast is a seasoned legal content creator and law research specialist with 15+ years of experience in legal writing, legal research, and publishing educational law content. Specializing in Personal Injury, Family, Business, Immigration, Criminal, Tax, and Real Estate Law, Beast creates accurate, well-researched, and SEO-optimized legal guides that help readers understand complex legal topics with confidence. Every article is written with a focus on accuracy, trust, and Google's E-E-A-T guidelines, making Jurnza.com a reliable source for legal information and legal services.
